Buying
Why Buying Below Your Maximum Budget Can Be a Smart Move
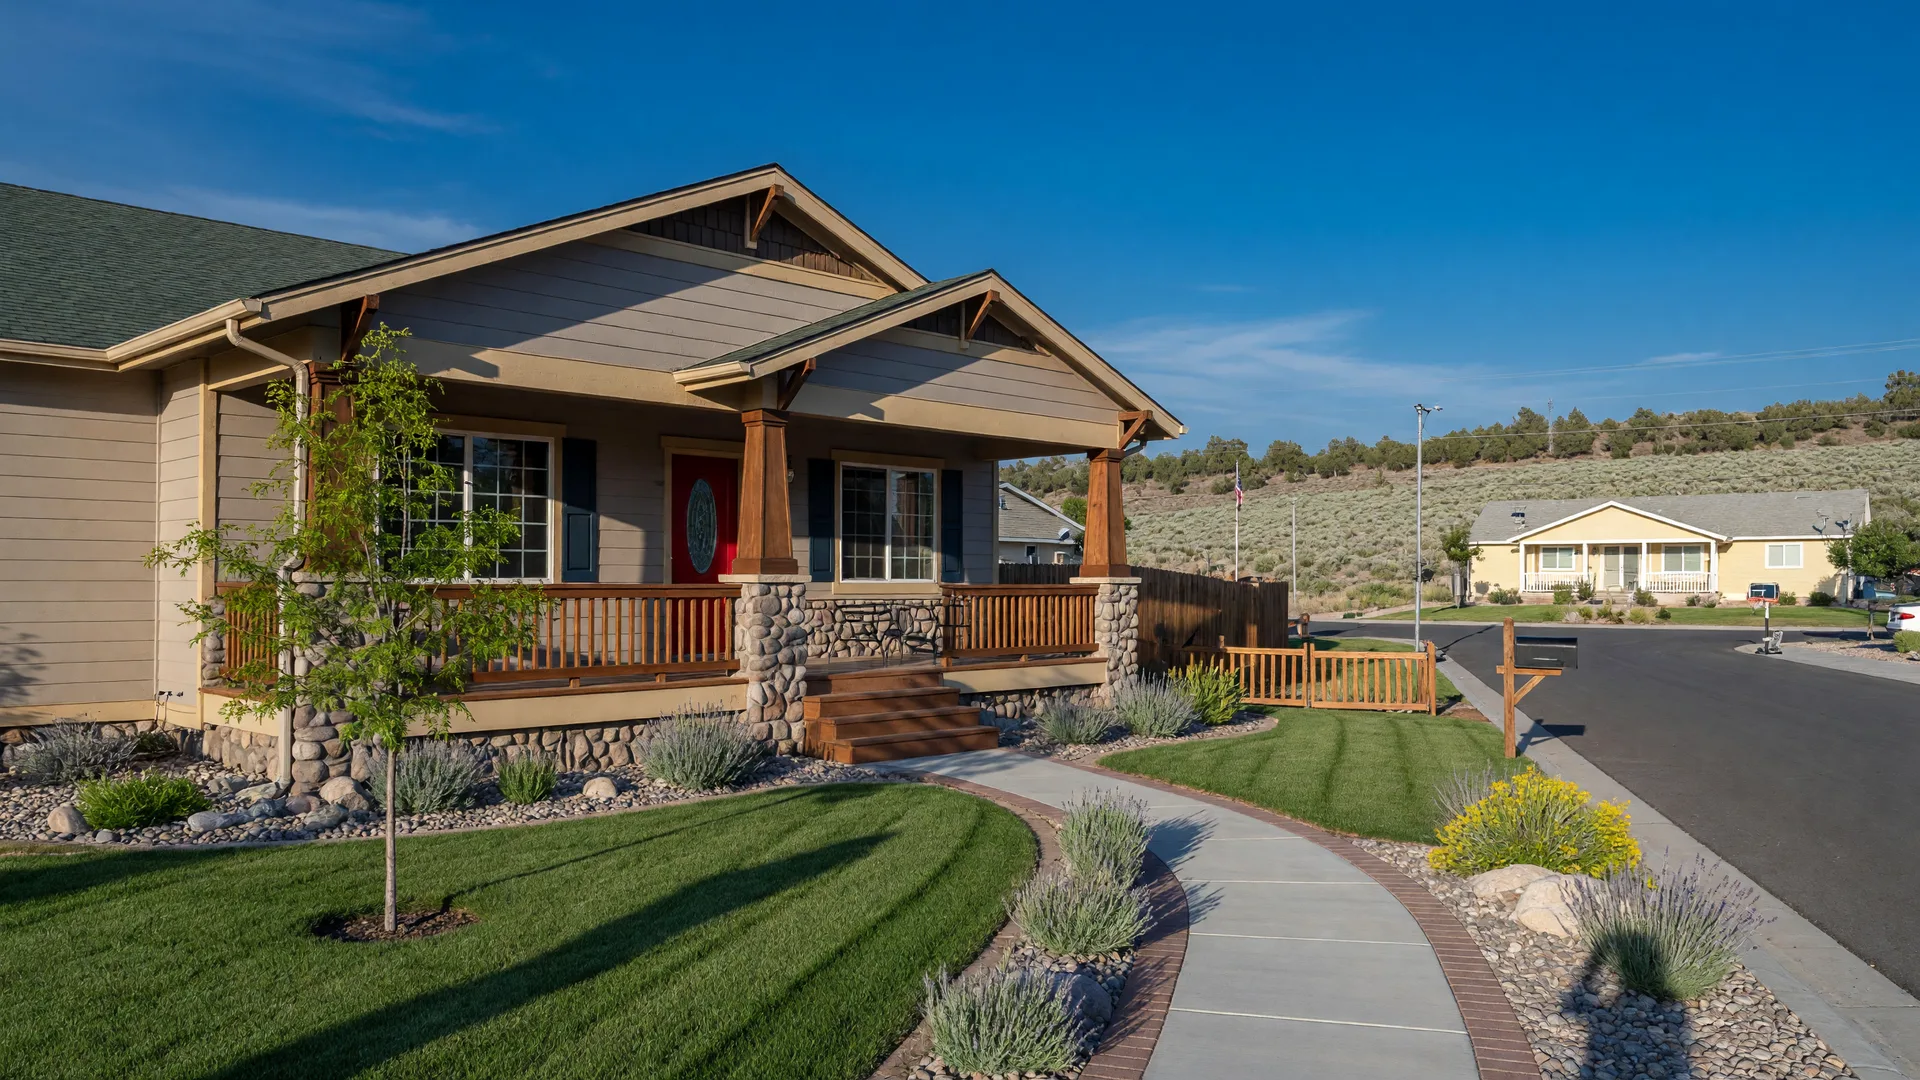
The number a lender approves you for is a ceiling, not a target. I have watched buyers stretch to that ceiling and then spend their first two years in a house feeling the squeeze, while neighbors who bought below their maximum slept fine and saved. Buying under your limit is not settling. It is usually the smartest financial decision in the whole purchase.
Real ownership costs more than the payment
Property taxes, insurance, utilities, and upkeep all scale with the house. Northern Nevada homes also carry seasonal realities, snow removal, irrigation, heating through real winters, that a California budget never included. A house at the top of your approval leaves no room for those second-layer costs, and they are guaranteed, not optional.
Life changes fast
The buffer below your maximum is what keeps a house livable through the unexpected: a new job, a new baby, a parent who needs help, a market that shifts. A payment that leaves a comfortable gap each month means choices stay yours. A payment that eats the whole paycheck means the house owns you.
The market rarely punishes restraint
A slightly smaller or slightly older home in a great neighborhood often appreciates right alongside the fanciest house on the block, without the carrying costs of keeping up with it. And when the market cools, the buyer with margin can ride it out, renovate, or sell on their own timeline. Leverage cuts both ways, and the less you owe, the better you sleep.
What to do with the gap
The space between your approval and your purchase price is a real asset. Put it toward a healthy emergency fund, extra principal payments, the upgrades that make the house feel like yours, or your next move, because most buyers do move again. Every dollar you do not spend on the mortgage is a dollar with options, and even a modest monthly surplus, invested steadily, becomes the down payment fund for the next house.
The gap is not wasted money
Some buyers worry that buying below their maximum means leaving value on the table, as if the extra approval amount were a coupon about to expire. It is not. That gap funds the life the house is supposed to support: family trips, savings for the kids, the remodel you will actually enjoy, or simply the freedom of a smaller payment. A house you can afford comfortably beats the house that impresses neighbors and worries you.
A local tip: test-drive your numbers before you offer. Plug the full monthly reality, payment, taxes, insurance, utilities, and a maintenance reserve, into a spreadsheet and live with that number for a month. If it feels fine, you are in the right range.
The buyers guide walks through building your offer around the number that fits, and the market updates page helps you understand what your price range is actually buying right now.
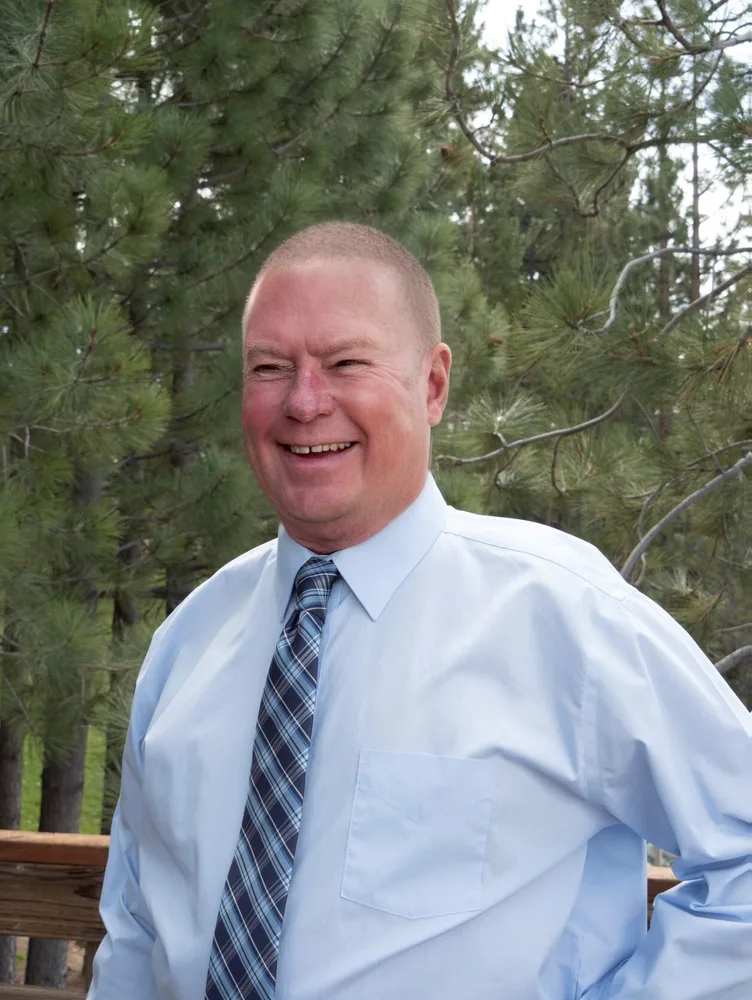
Dennis Lindsay
Broker Associate · 40+ Years in Northern Nevada
Licensed in both California and Nevada, Dennis has spent more than 40 years helping families buy and sell homes across Carson City, the Carson Valley, Reno, and Lake Tahoe. Call him at (530) 318-2369.
Let's Find Your Comfortable Number
Tell me your monthly comfort zone, not your maximum, and I will build the search around the home that fits the life you actually want.